

The company has lately reached records in the market with Amazon shares trading at an all-time high of 254 and its present level standing at 232.16.
Whether or not the investment in this technology conglomerate is a good one in the existing market excitement, is the question.
Cloud Power Surge
The primary driver of Amazon growth is its Amazon Web Services (AWS). During the third quarter, AWS has updated the revenues by 20.2% to the point of $33 billion and a significant backlog of $200 billion of sources based on artificial-intelligence demand.
Amazon says its custom silicon, Graviton and Trainium, delivers better price-performance than rival chips, though independent benchmarks remain limited.
Amazon has already allotted capital expenditure of $125 billion in 2025 which is set to experience growth in 2026, as Wall Street responded with an 11% stock surge to facilitate expansion of data-centers hence capacity in 2027.
TD Cowen noted that it sees three key drivers for Amazon shares in 2026.
These include accelerating AWS revenue growth, eCommerce and advertising momentum, and continued operating margin expansion.
AWS revenue growth is anticipated to accelerate in 4Q25 and accelerate further in both ’26 and ’27. This growth is being fueled by
“Core and AI workload demand and higher AI capacity amid the historic AI infrastructure build.”
Ads Steal the Show
It saw an increase of advertising revenue of 24% in the third quarter by $17.7 billion and it is estimated to grow more in 2026.
The main sources of conversion are Prime Video services and products that are advertised which can be improved by partnership with Netflix and Spotify.
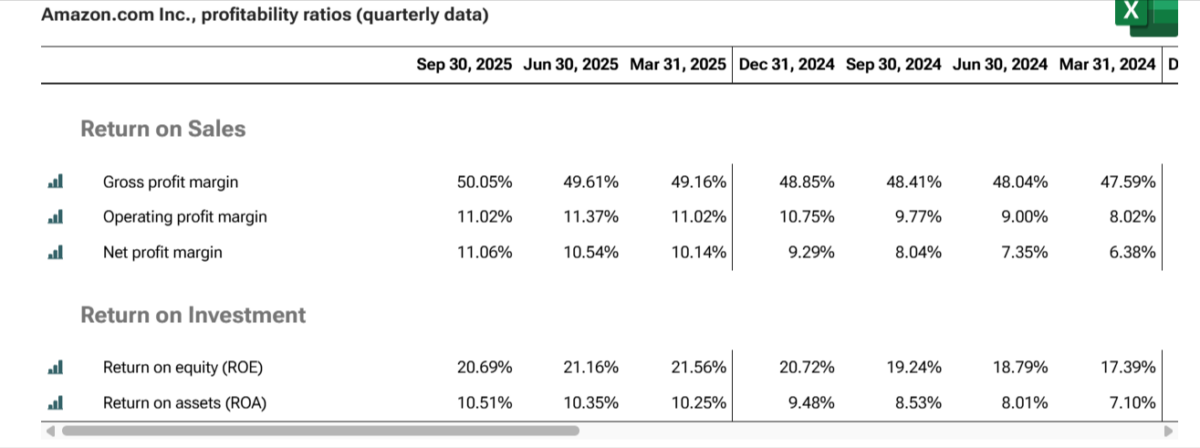
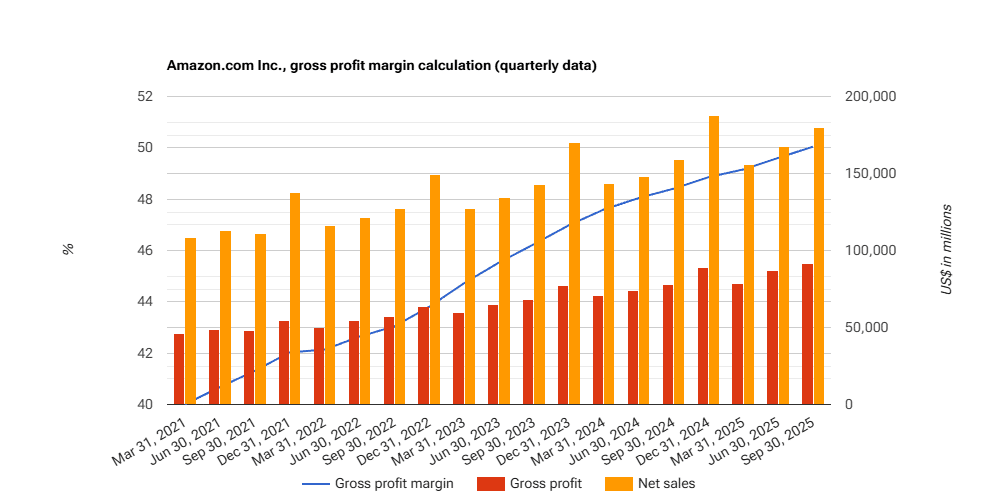
The company's overall gross profit margin has increased to 50.05% which is higher compared to that of the past fiscal year.
Valuation Check
Amazon has 2.48 trillion in market cap, and a forward-earnings multiple near 40x, a premium to most megacap peers that rests on AI-driven growth continuing.
Although temporary retreats might be brought about by profit making activity, this market noise should have less weight rather than the long run growth projections of the company.
Most importantly, investments completed by Amazon in artificial-intelligence supporting infrastructure place the company ahead of other hyperscalers.
Future Outlook
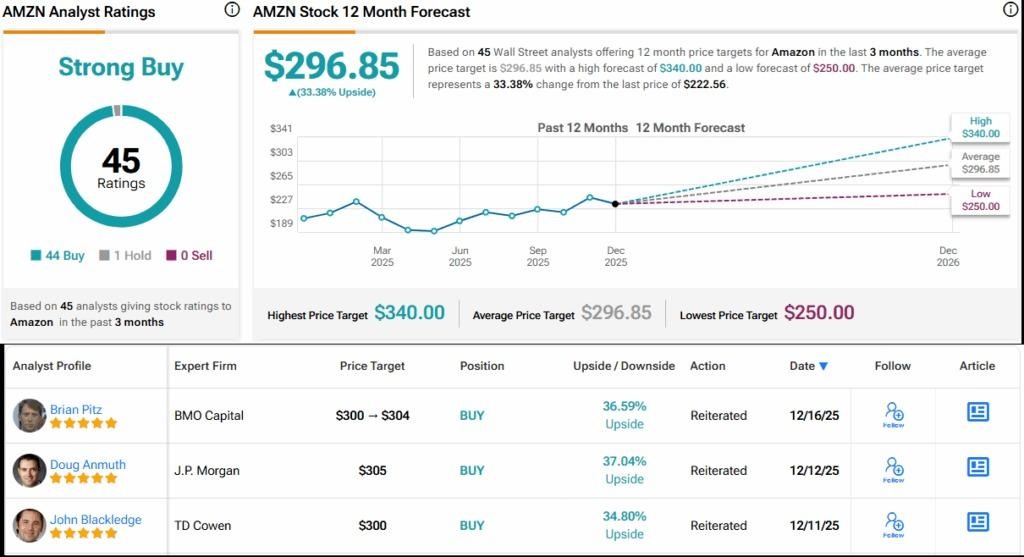
Looking forward from here, Blackledge rates Amazon’s stock as a Buy, with a $300 price target that indicates potential for a 35% upside in the coming year.
Similarly, Amazon’s Strong Buy consensus rating is based on 45 analyst reviews, with a highly lopsided split of 44 Buys to 1 Hold.
The shares are currently priced at $222.56 and the $296.85 average price target implies a one-year gain of 33%.
The future looks bright if the artificial-intelligence spending will speed up, thus compensating patient shareholders.
Disclaimer
This article is for informational purposes only and does not constitute financial, investment, tax, or legal advice. Market data, tax rules, and prices can change after the article date. TECHi and its authors may hold positions in securities or digital assets mentioned. Always conduct your own research and consult a licensed financial, tax, or legal professional before making decisions.
About the Author
Warisha Rashid covers AI stocks and crypto markets for TECHi. Recent work explains what changed when Worldcoin cut its WLD token unlock, how AMD's rack-scale Helios design fits an asset-light strategy, and how Nvidia, Alphabet, Palantir, AMD and Broadcom compare as AI businesses.

Comments