
Adobe headquarters in San Jose, California, photographed October 21, 2007. Archival photograph by Coolcaesar / Wikimedia Commons, CC BY-SA 4.0. Cropped and official TECHi mark added; adapted photograph shared under the same license.
Adobe’s Semrush released its first UK benchmark for AI-search visibility on Tuesday, October 13, finding that brands’ prominence varies by market and platform—and that being named in an answer often does not bring a matching position among its cited sources. The findings put a practical question behind Adobe’s investment in the business: can it sell marketers a way to close those gaps, rather than simply another dashboard that displays them?
The announcement, issued at 5:01 a.m. EDT, accompanied Semrush’s Spotlight event in London. The new report compares seven monthly measurements from January through July 2026. It is new research published today, not evidence that AI-search behavior suddenly changed this morning.
For Adobe stock, the opportunity extends beyond generating pictures, documents or marketing copy. Adobe also wants to help companies get found when customers ask AI systems what to buy. Its own acquisition accounting provides a useful measure of the stakes: Adobe paid $1.874 billion for Semrush, with about two-thirds of that purchase price recorded as goodwill. Today’s study helps explain the strategic ambition; proving the financial return requires different evidence.
What the UK study actually found
Semrush’s 57-page report separates two measures that can easily be mistaken for each other. A mention records a brand appearing in an AI answer. A citation records a website appearing as a source. Neither, on its own, establishes a recommendation, a visit to the company’s website or a sale.
That distinction produces a striking example. Tesco and Asda appeared among the top 100 mentioned brands on all four studied platforms in every measured month. Yet in July, Tesco’s website ranked 25th among ChatGPT’s UK cited domains, while Asda’s ranked 606th. On Gemini, their citation ranks were much closer: 29th and 60th.
Those are rankings within each platform’s UK dataset. They do not mean Tesco received 24 times Asda’s traffic, or that changing a website would automatically close the gap. They do show why a marketing department could be satisfied with a brand-mention score while missing a much weaker source position.
| Website | ChatGPT citation rank | Gemini citation rank |
|---|---|---|
| Tesco (tesco.com) | 25 | 29 |
| Asda (asda.com) | 606 | 60 |
The difference persisted beyond individual retailers. Averaged across 22 categories and four platforms, the overlap between the top-100 mention and citation lists stayed below half in each measured month in both countries. This is an average across the study’s categories and platforms, not a claim that every individual list had less than 50% overlap.
For Adobe, the commercial opening is the work needed after that discovery: deciding which pages or third-party sources to investigate, correcting inaccurate information, and measuring whether a change produces a useful outcome. Counting appearances is only the first step.
A UK strategy cannot simply inherit the US score
The country comparison makes the potential workload larger. The report identified 24 UK domain records and 36 US records that appeared in all four platforms’ top-100 mention lists in every month. Only 15 domain records belonged to both groups.
Subtracting the shared 15 leaves nine records unique to the UK group and 21 unique to the US group. These are website-domain records, not a count of unique companies: a multinational can appear through different national addresses. Investors should resist converting those counts into a market-share estimate or a forecast of customer demand.
A second comparison shows why the difference matters to the people buying software. News and information sites accounted for a seven-month average of 29.5% of citation weight among ChatGPT’s top 100 UK source domains, against 19.6% in the US. TECHi calculates a 9.9-percentage-point difference, using 29.5 minus 19.6.
The denominator matters. This is the citation total within each market’s top-100 source list, not all ChatGPT answers or all citations everywhere. The category labels describe domains, rather than identifying every individual cited page as a news article.
Even with those limits, the implication is useful: a business operating in both markets may need different source investigations and different ways to judge progress. Translating an American campaign into British English would not, by itself, address that measurement problem.
Why this belongs in the Adobe investment debate
Adobe completed the Semrush acquisition on April 28. At the time, it described combining Semrush’s search intelligence with products including Experience Manager, Adobe Experience Platform, Adobe Commerce, Adobe LLM Optimizer and Brand Concierge to connect discovery with customer engagement.
That creates a possible path through a marketing budget. A company first needs to understand where its brand appears. It may then need to improve its content or customer experience, publish changes, and assess what happened afterward. Adobe’s proposition is stronger if its products make those tasks work together and reduce the customer’s effort.
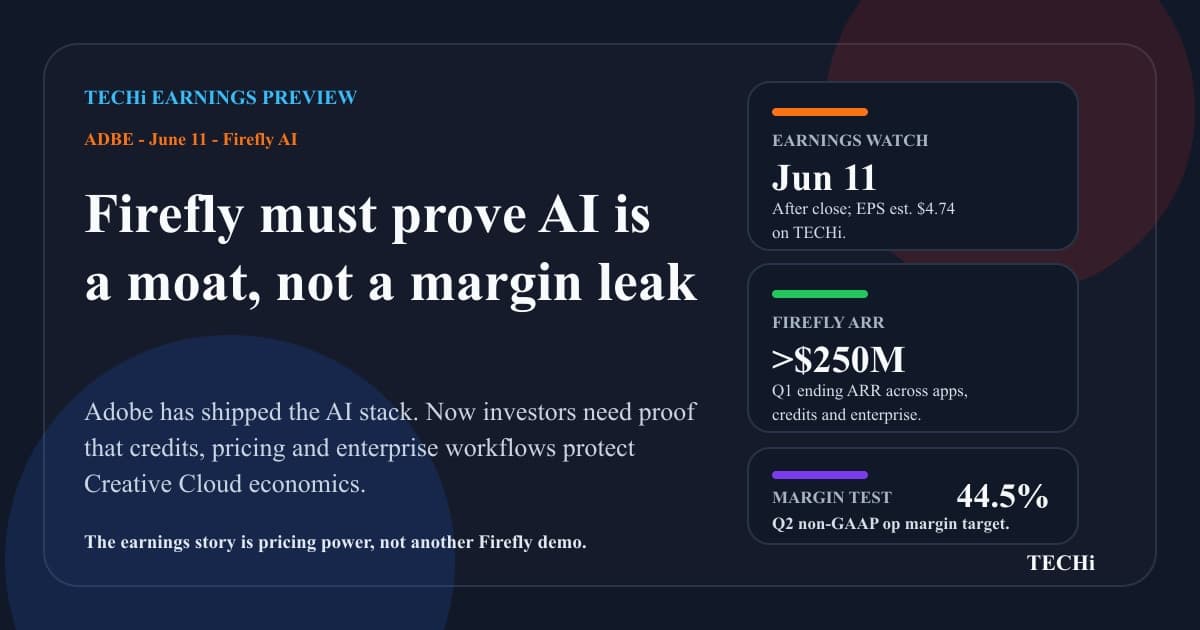
This is different from the question in TECHi’s earlier Adobe analysis of Firefly and paid AI adoption. That piece examined whether creative AI usage could support pricing. Semrush introduces another potential source of demand: helping marketing teams navigate the AI interfaces that stand between their content and prospective customers.
There is a plausible advantage here. A supplier already involved in a company’s content and customer-experience systems may have an easier route to showing what changed after an intervention. But integration is not automatic, and a broad product portfolio does not establish that customers will pay more for a combined offering.
Today’s release announces research. It does not announce a new revenue contract, identify incremental Semrush sales from the UK findings, or raise Adobe’s earnings outlook. The stock relevance is an execution question supported by new evidence about customer needs, rather than a reported financial windfall.
The filing shows how much remains to be earned
Adobe’s latest quarterly filing, covering the period ended August 28, gives more precise acquisition figures than the approximately $1.9 billion equity value announced when the deal was agreed.
The final purchase-price allocation lists $1.874 billion in total consideration and $1.251 billion in goodwill. Dividing $1.251 billion by $1.874 billion gives 66.8%, rounded to one decimal place. Adobe says that goodwill primarily reflects the assembled workforce and expected benefits from combining Semrush’s platform with Adobe’s existing offerings.
Goodwill is an accounting allocation, not a separate cash payment, a revenue forecast or proof that Adobe overpaid. A high proportion alone cannot establish that the acquisition will succeed or fail. It does underline that much of the recorded purchase value rests outside separately identified assets, making the quality of the combined business important to assessing the investment.
The same filing says Adobe did not present separate financial results and pro forma information for the acquisition because its impact on the consolidated statements was not material. That limits what an outside investor can independently calculate about Semrush’s contribution from this filing. It does not mean the business had no revenue or no strategic value.
Adobe reported fiscal third-quarter revenue of $6.76 billion, up 13% from a year earlier, and ended the quarter with $27.50 billion in annualized recurring revenue. Its filing says the ARR growth included a Semrush contribution, alongside strength elsewhere in the portfolio. It does not isolate how much came from selling the new combination to existing customers.
That is the hurdle for a company of Adobe’s scale. An interesting measurement market must eventually produce enough durable revenue or customer retention to matter within a much larger subscription business. Acquired revenue and genuinely additional sales from integration answer different questions.
The strongest counterargument: a problem is not a paid market
Semrush sells software addressing the very difficulty its research describes. That commercial interest does not invalidate the observations, but readers should treat the findings as vendor-produced research rather than an independent test of whether Adobe’s products improve customer profits.
There is also a credible alternative to the optimistic investment case. Marketing teams might handle some of this work with existing analytics tools, specialist providers or a limited manual audit. A visible gap may deserve investigation without justifying a large new software contract. The report itself describes a small manual audit as a possible starting point.
More importantly, an AI answer can cite a third-party page that already describes a brand accurately. Moving the brand’s own website higher in a source ranking may be less valuable than it first appears. A campaign optimized only for citation counts could absorb staff time while doing little for customer understanding or sales.
The valuable product would help a customer decide when to act and when to leave a satisfactory result alone. That is harder than presenting a rising score. It requires reliable measurement, useful recommendations and evidence that the resulting work earns its cost.
Adobe’s case would strengthen if customers documented that integration shortened the path from diagnosis to an effective change, then renewed or expanded their spending. It would weaken if the main response were more free experimentation, greater service work or bundled features that added cost without supporting higher revenue.
The study’s limits change how investors should use it
The methodology uses monthly pools of 2.5 million UK prompts and 25 million US prompts for ChatGPT, Gemini and Google AI Mode. Google AI Overviews uses a separate keyword-based collection with a varying monthly size. Those pools must not be added into one supposedly unique total or used to compare raw market volumes.
Semrush also says the report measures recurring relationships rather than growth. A range shows the lowest and highest separate monthly results; it is not necessarily a rise from January to July. The analysis does not isolate platform changes from collection differences, so it cannot establish that a particular model update caused a shift.
These qualifications make the report a starting point for business investigation. They prevent a broader claim that UK consumers are adopting AI faster, that one platform is commercially superior, or that Adobe’s addressable revenue increased by the size of a visibility gap.
For the next Adobe results, three forms of evidence would make this story more financially meaningful: a clearer separation of acquired growth from additional sales, examples linking the combined products to measurable customer outcomes, and evidence that those outcomes support renewals or expansion. Readers can follow the company’s reported numbers on TECHi’s Adobe financials page, while keeping product adoption claims separate from recognized revenue.
Tuesday’s findings give Adobe a specific problem to sell against: brands can be prominent in AI answers yet poorly represented among the sources, with different gaps in different countries. Whether that becomes a durable advantage for ADBE depends on the next step—getting customers to pay for improvements they can verify.

Disclaimer
This article is for informational purposes only and does not constitute financial, investment, tax, or legal advice. Market data, tax rules, and prices can change after the article date. TECHi and its authors may hold positions in securities or digital assets mentioned. Always conduct your own research and consult a licensed financial, tax, or legal professional before making decisions.
About the Author
Muhammad Zeshan Sarwar is Editor-in-Chief of TECHi. His published work covers public companies, AI infrastructure and cryptocurrency networks. His portfolio includes company financial results, stock forecasts and comparisons, and explanations of blockchain upgrades and crypto-market developments.

Comments