

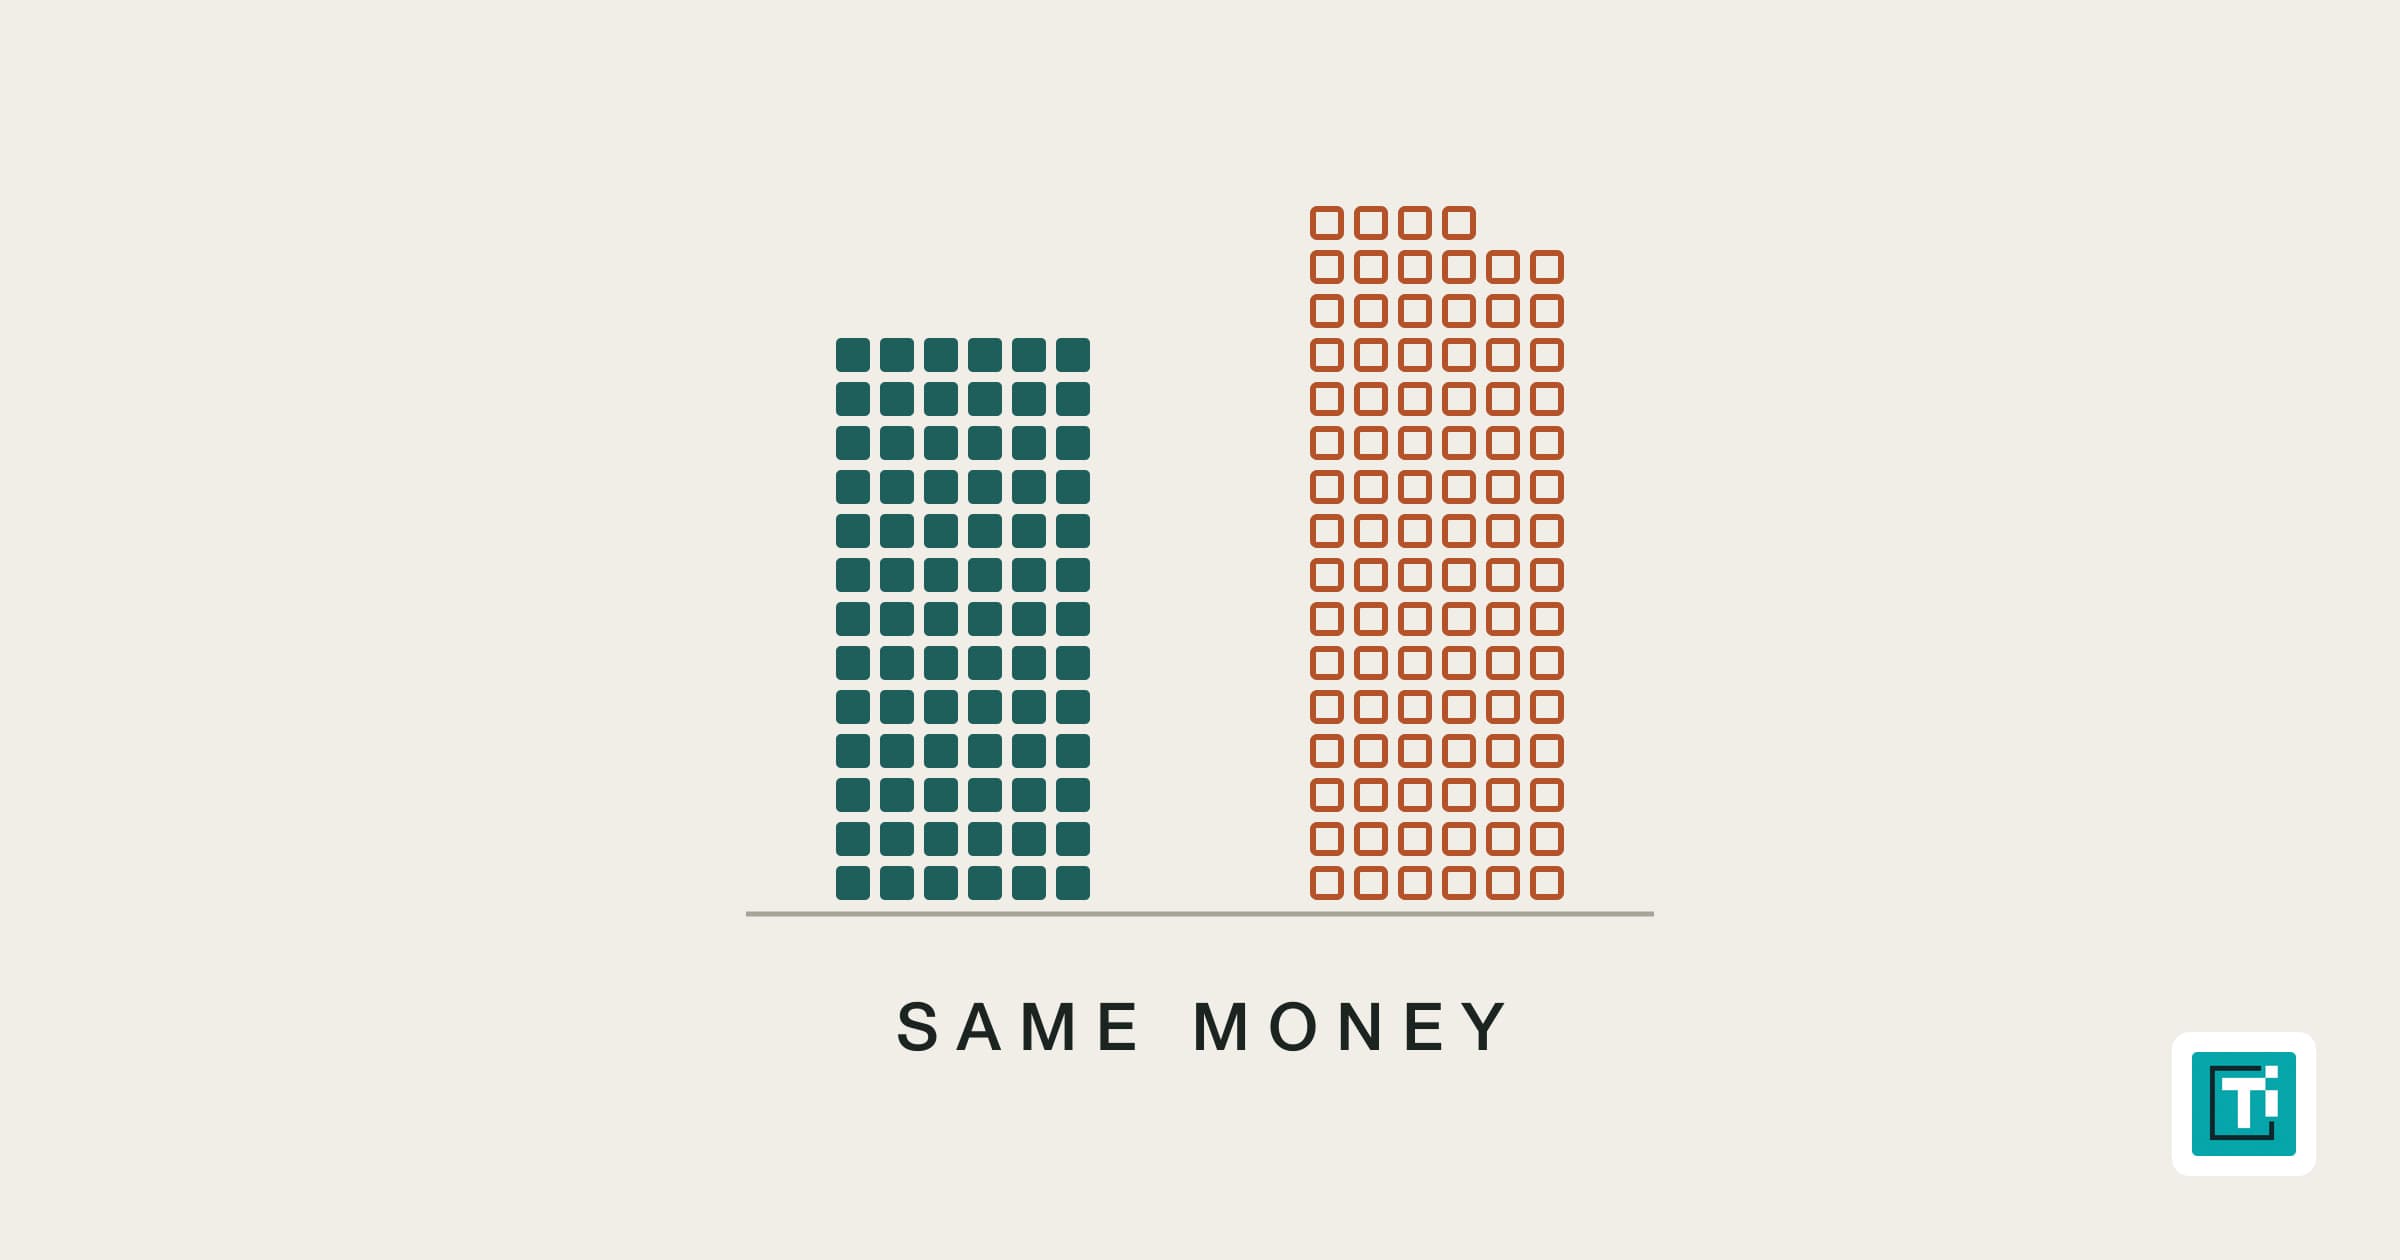
Editorial illustration. Keysight's quarterly orders (purple) and revenue (dark) over the six quarters to October 2026, drawn to scale; the shaded area is the gap between them. Illustration: TECHi, from company filings.
Keysight Technologies reported revenue of $1.994 billion for the three months to October 31, 2026, up 41% from a year earlier and above the top of its own forecast, according to results released after the market closed on Thursday, November 19. That is $6 million short of the company's first $2 billion quarter. It forecast one for the quarter now under way, with revenue of $2.04 billion to $2.06 billion.
The orders say more than the revenue. Keysight took $2.34 billion of orders in the quarter, the third in a row above $2 billion, and over its fiscal year orders ran $969 million ahead of revenue, TECHi's calculation from the company's filings shows. The forecast still points to slower growth, about 28% at its midpoint after 41%. The stock was down 0.1% at $281.27 at 9:49 a.m. Eastern on Friday, shortly after the market opened.
Key Takeaways
- The quarterRevenue was $1.994 billion, up 41% and $44 million above the top of Keysight’s forecast, but $6 million short of $2 billion.
- The ordersOrders were $2.34 billion, the third quarter running above $2 billion. Over the fiscal year they exceeded revenue by $969 million.
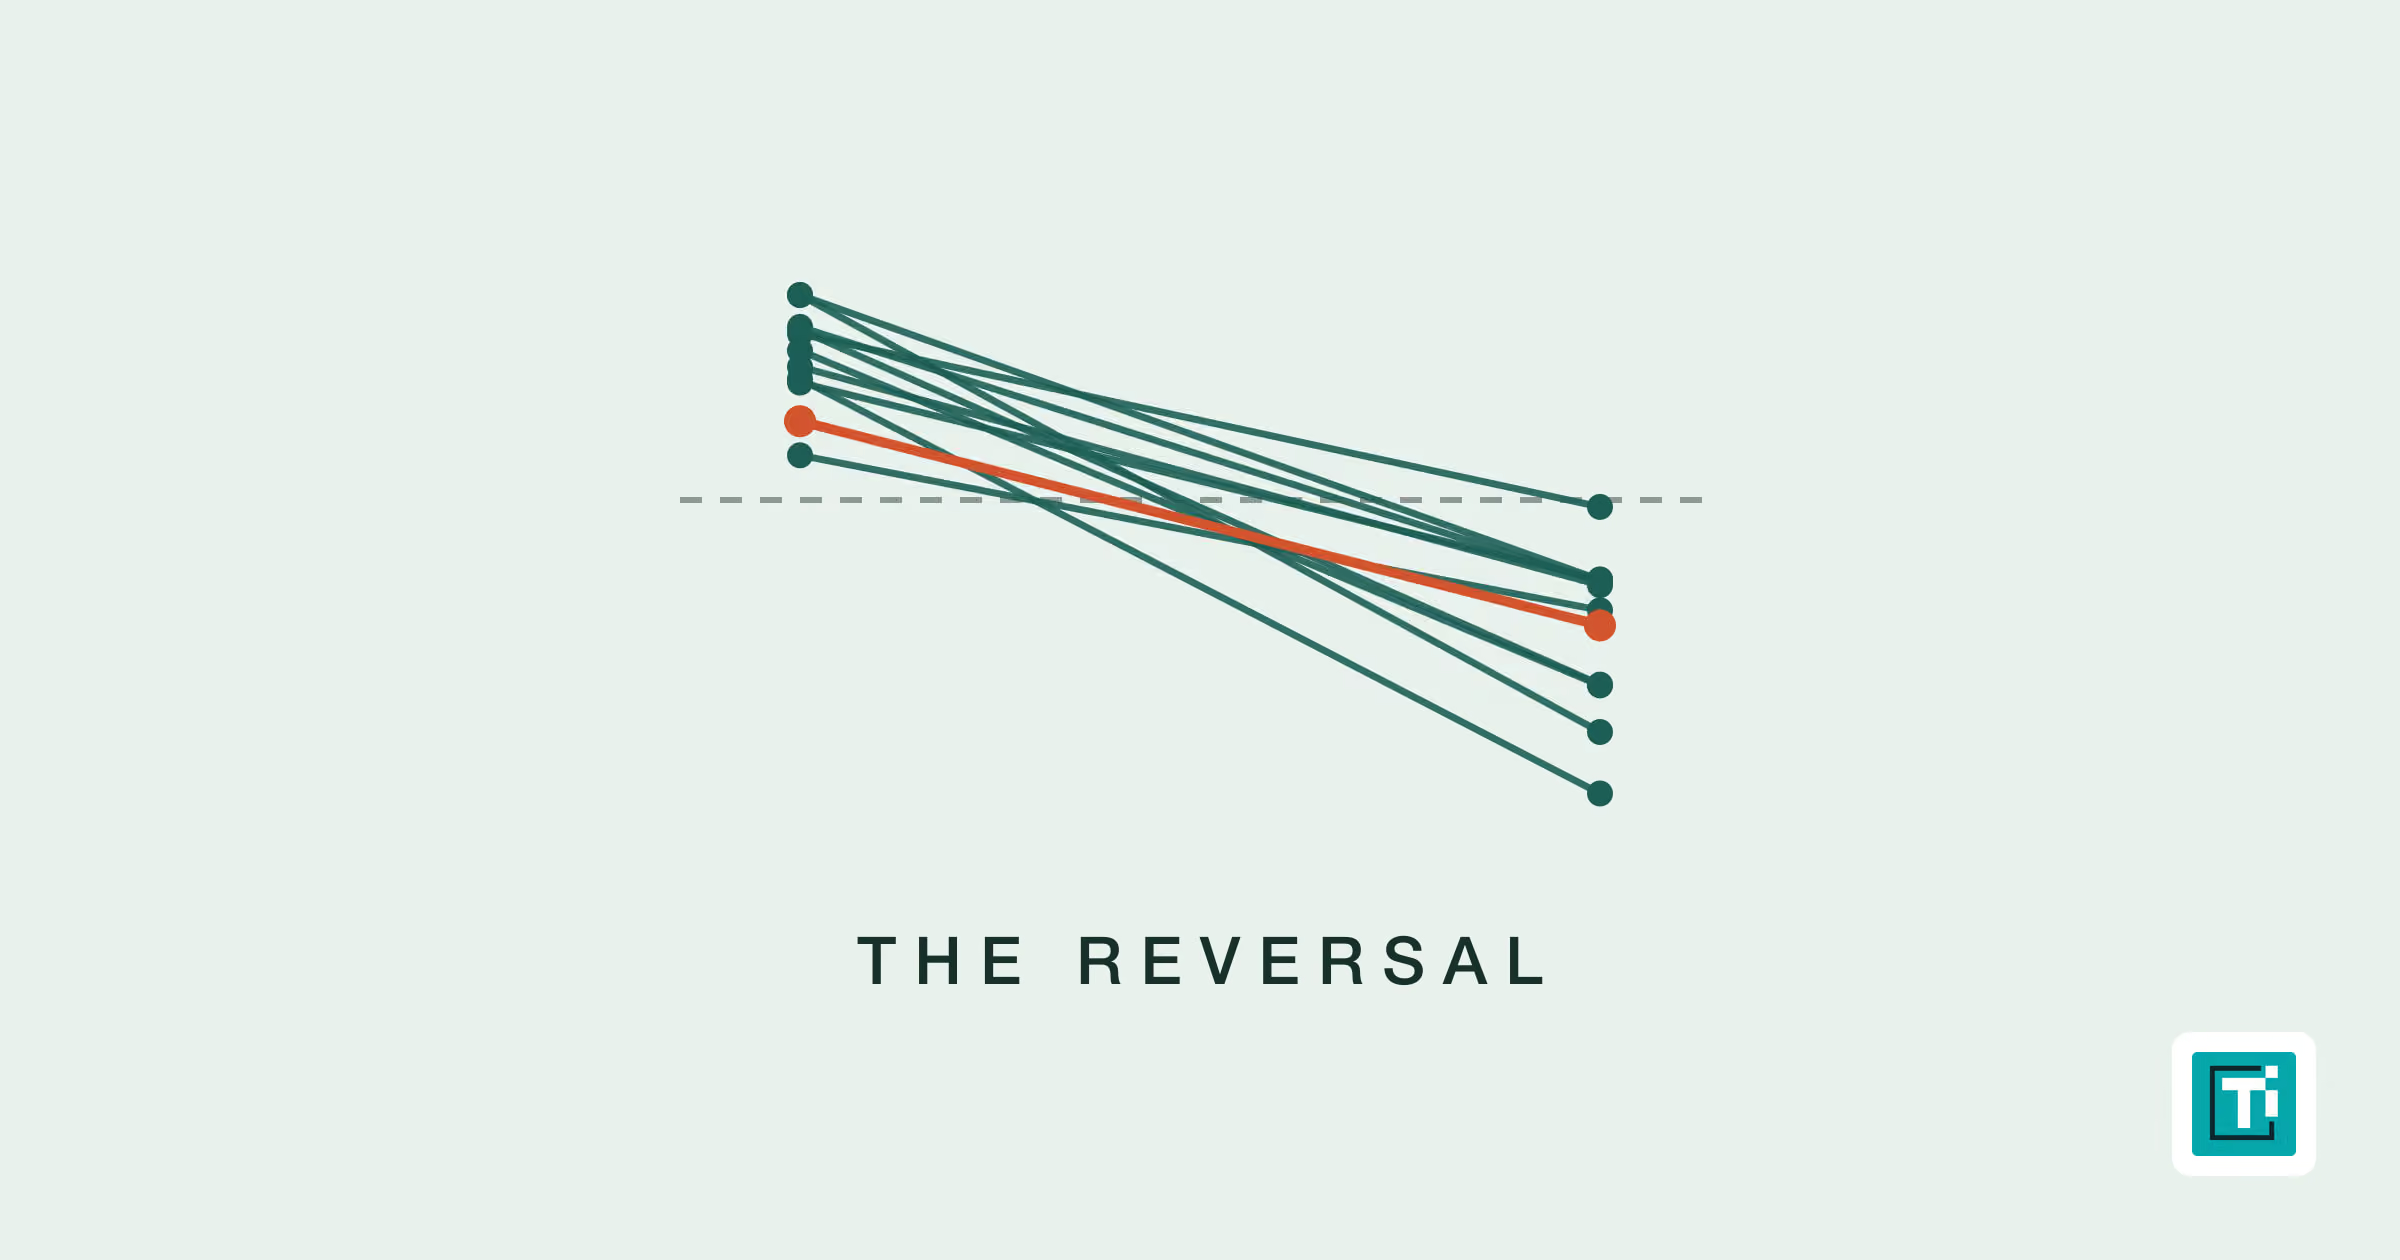
- The recordEach of the last six quarters has come in above the top of the company’s revenue range, by an average of $42 million.
- The forecastKeysight expects $2.04 billion to $2.06 billion this quarter. The midpoint is growth of 28%, down from 41%.
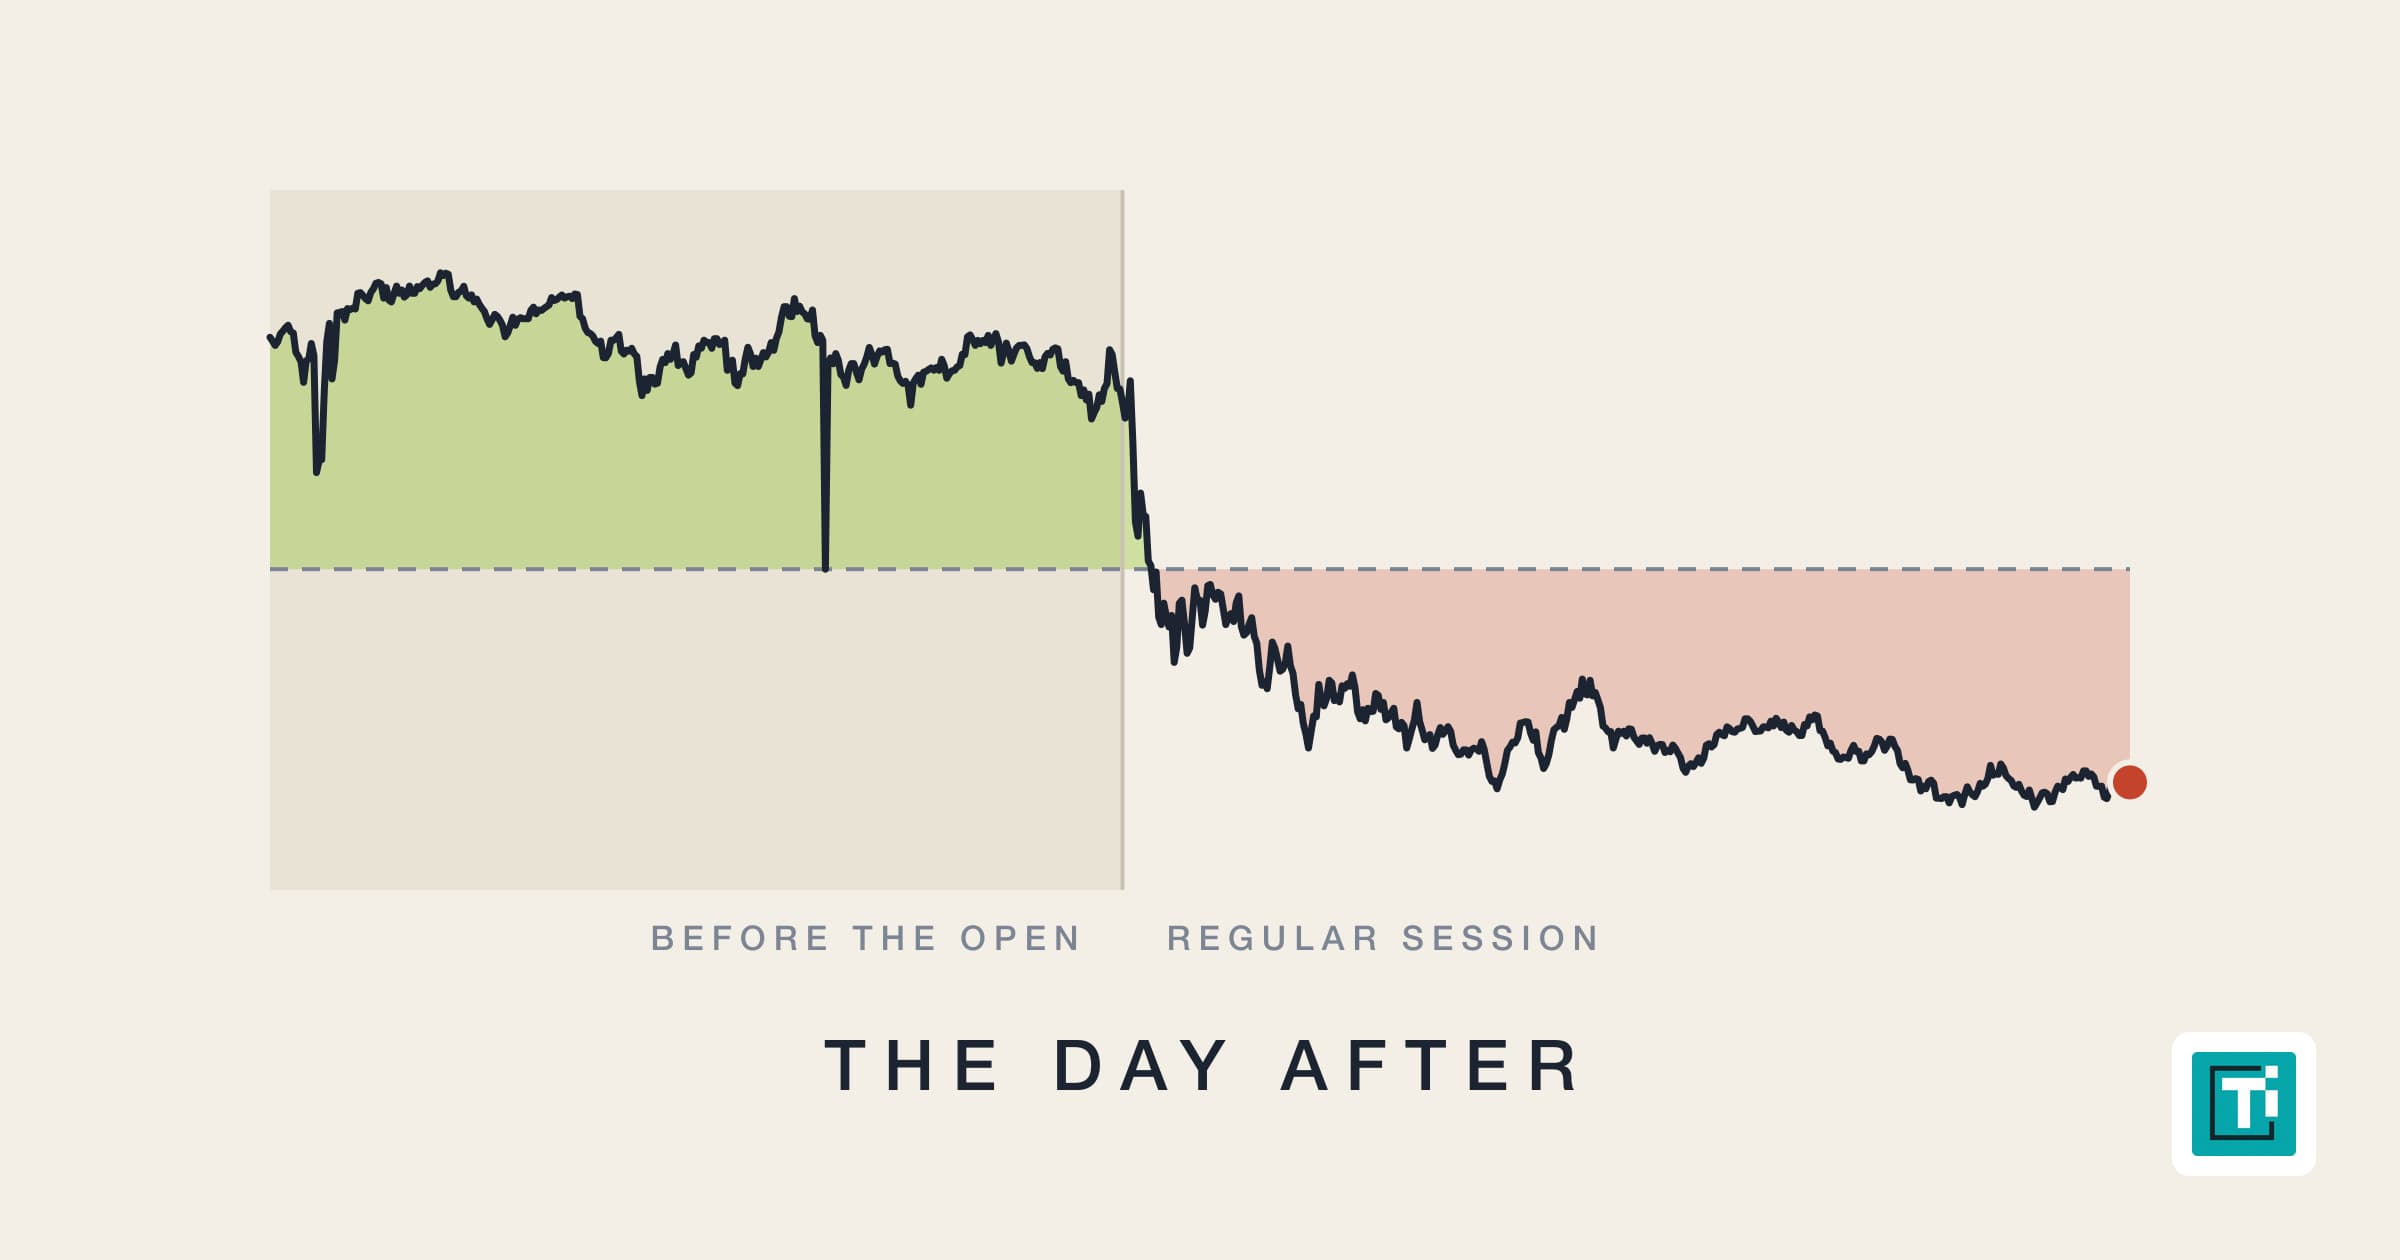
- The stockThe shares were down 0.1% at $281.27 shortly after Friday’s open, at 9:49 a.m. Eastern. They fell on the day after four of the last six reports.
How did Keysight do against its forecast?
It beat it, as it has every quarter for a year and a half. Keysight makes the test and measurement equipment that engineers use to design and check electronics, and much of its recent growth has come from the networking gear inside AI data centers.
In August the company told investors to expect revenue of $1.93 billion to $1.95 billion and adjusted earnings of $3.34 to $3.40 a share. Revenue came in $44 million above the top of that range. Adjusted earnings were $3.61 a share, 21 cents above the top and 89% more than a year earlier. Net income was $486 million, or $2.82 a share.
In each of the last six quarters revenue has landed above the top of the company's range. The average margin over the six is $42 million. One of them, the April quarter, looks smaller than it was: revenue that quarter was reduced by $40 million that Keysight set aside to refund tariff surcharges to customers.
Cash followed. Operations generated $507 million in the quarter and free cash flow was $465 million, 23% of revenue. Keysight ended the year with $2.92 billion of cash.
For the full fiscal year revenue was $7.16 billion, up 33%. Adjusted earnings were $11.72 a share, up 64%, and free cash flow was $1.75 billion.
| Quarter ended | Forecast range | Reported revenue | Above top of range | Orders |
|---|---|---|---|---|
| July 2025 | $1.305B to $1.325B | $1.352B | $27M | $1.340B |
| October 2025 | $1.370B to $1.390B | $1.419B | $29M | $1.533B |
| January 2026 | $1.530B to $1.550B | $1.600B | $50M | $1.645B |
| April 2026 | $1.690B to $1.710B | $1.717B | $7M | $2.051B |
| July 2026 | $1.730B to $1.750B | $1.846B | $96M | $2.091B |
| October 2026 | $1.930B to $1.950B | $1.994B | $44M | $2.339B |
Why do the orders matter?
Orders are what customers have committed to buy. Revenue is what has been delivered and billed. When orders run ahead of revenue, work is piling up to be delivered later.
That has been the pattern all year. Orders in the October quarter were $2.34 billion, 53% more than a year earlier and 12% more than in the July quarter. They were 1.17 times the quarter's revenue.
Orders exceeded revenue in each of the four quarters of the fiscal year, by $45 million, $334 million, $245 million and $345 million. That adds up to $969 million. Full-year orders were $8.13 billion, up 49%, against revenue growth of 33%.
It was not so a year and a half ago. In the July 2025 quarter orders of $1.34 billion were slightly below revenue of $1.35 billion.
Two cautions apply. Orders can be delayed or cancelled, and the release does not give a backlog figure. Part of the growth was also bought. Keysight completed three acquisitions in October 2025, the largest of them the network-testing company Spirent, and its quarterly report for July said acquisitions added five points to order growth and six to revenue growth in that quarter.
Where is the growth coming from?
From communications, and within that from AI networking. The Communications Solutions Group reported revenue of $1.50 billion, up 51% and three-quarters of the company's total. Its commercial communications business grew 73%. Its aerospace, defense and government business grew 7%.
The smaller Electronic Industrial Solutions Group, which serves chipmakers, carmakers and general electronics, reported revenue of $498 million, up 16%.
Keysight's July report said the commercial growth came from customers developing faster data center links, at speeds of 400, 800 and 1,600 gigabits a second, and from makers of optical transceivers adding factory capacity to meet demand for AI. One of those makers, Coherent, spent $775.5 million on capital projects in a single quarter, as TECHi reported on Thursday.
What does the new forecast imply?
A first $2 billion quarter, and slower growth. For the three months to the end of January, Keysight expects revenue of $2.04 billion to $2.06 billion and adjusted earnings of $3.63 to $3.69 a share.
The midpoint, $2.05 billion, is 28.1% above the same quarter a year earlier and 2.8% above the quarter just reported. Growth in the October quarter was 40.5%. Part of the difference is the acquisitions. They closed in mid-October 2025, so from this quarter they are in both years' figures and no longer lift the comparison.
The company's record suggests the range is cautious. A year ago it forecast $1.53 billion to $1.55 billion for the same quarter and reported $1.60 billion. If revenue came in above the top by the six-quarter average of $42 million, it would be about $2.10 billion, growth of 31%. That would still be slower than the quarter just ended.
The earnings forecast is flatter. Its midpoint of $3.66 a share is 69% above a year earlier and 1.4% above the $3.61 just reported.
There is also a change at the top of the finance team. Chief financial officer Neil Dougherty steps down on December 18 and will be succeeded by Jason Kary, who runs the industrial group, the company said in a filing this month. These are the last results due before the handover.
How did the stock react?
Keysight closed at $281.42 on Thursday, down 1.7%, before the results came out. The Nasdaq Composite fell 2.25% the same day. On Friday the shares were at $281.27 at 9:49 a.m. Eastern, shortly after the open, down 0.1% from Thursday's close.
The first move after Keysight's results has not been a reliable guide. On the day after each of its last six reports the stock fell four times and rose twice: down 0.2%, down 3.0%, up 10.0%, up 23.1%, down 0.6% and down 6.3%. The 6.3% fall came in August, after a quarter with record orders and the largest beat of the six.
At Thursday's close the shares were up 38.5% this year and 27.5% below their closing high of $388.03, set on October 6. The company was worth about $47.9 billion, 24 times its adjusted earnings for the fiscal year. It had $983 million left at the end of July under a $1.5 billion share buyback program approved a year ago.
There is a case on each side. Orders are running well ahead of revenue, the company has beaten its own forecast in each of the last six quarters, and it converts about a quarter of its revenue into free cash flow. Against that, growth is set to slow as last year's acquisitions drop out of the comparison, AI stocks have fallen sharply this month, and a new finance chief takes over in four weeks.
What to watch
Friday's close, set against the pattern of the last six reports. The annual report, due in mid-December. The handover to a new finance chief on December 18. Results for the January quarter, expected in late February, will show whether revenue clears $2.06 billion and whether orders stay above $2 billion. TECHi's Keysight quote page carries the live price.

Disclaimer
This article is for informational purposes only and does not constitute financial, investment, tax, or legal advice. Market data, tax rules, and prices can change after the article date. TECHi and its authors may hold positions in securities or digital assets mentioned. Always conduct your own research and consult a licensed financial, tax, or legal professional before making decisions.

Comments