
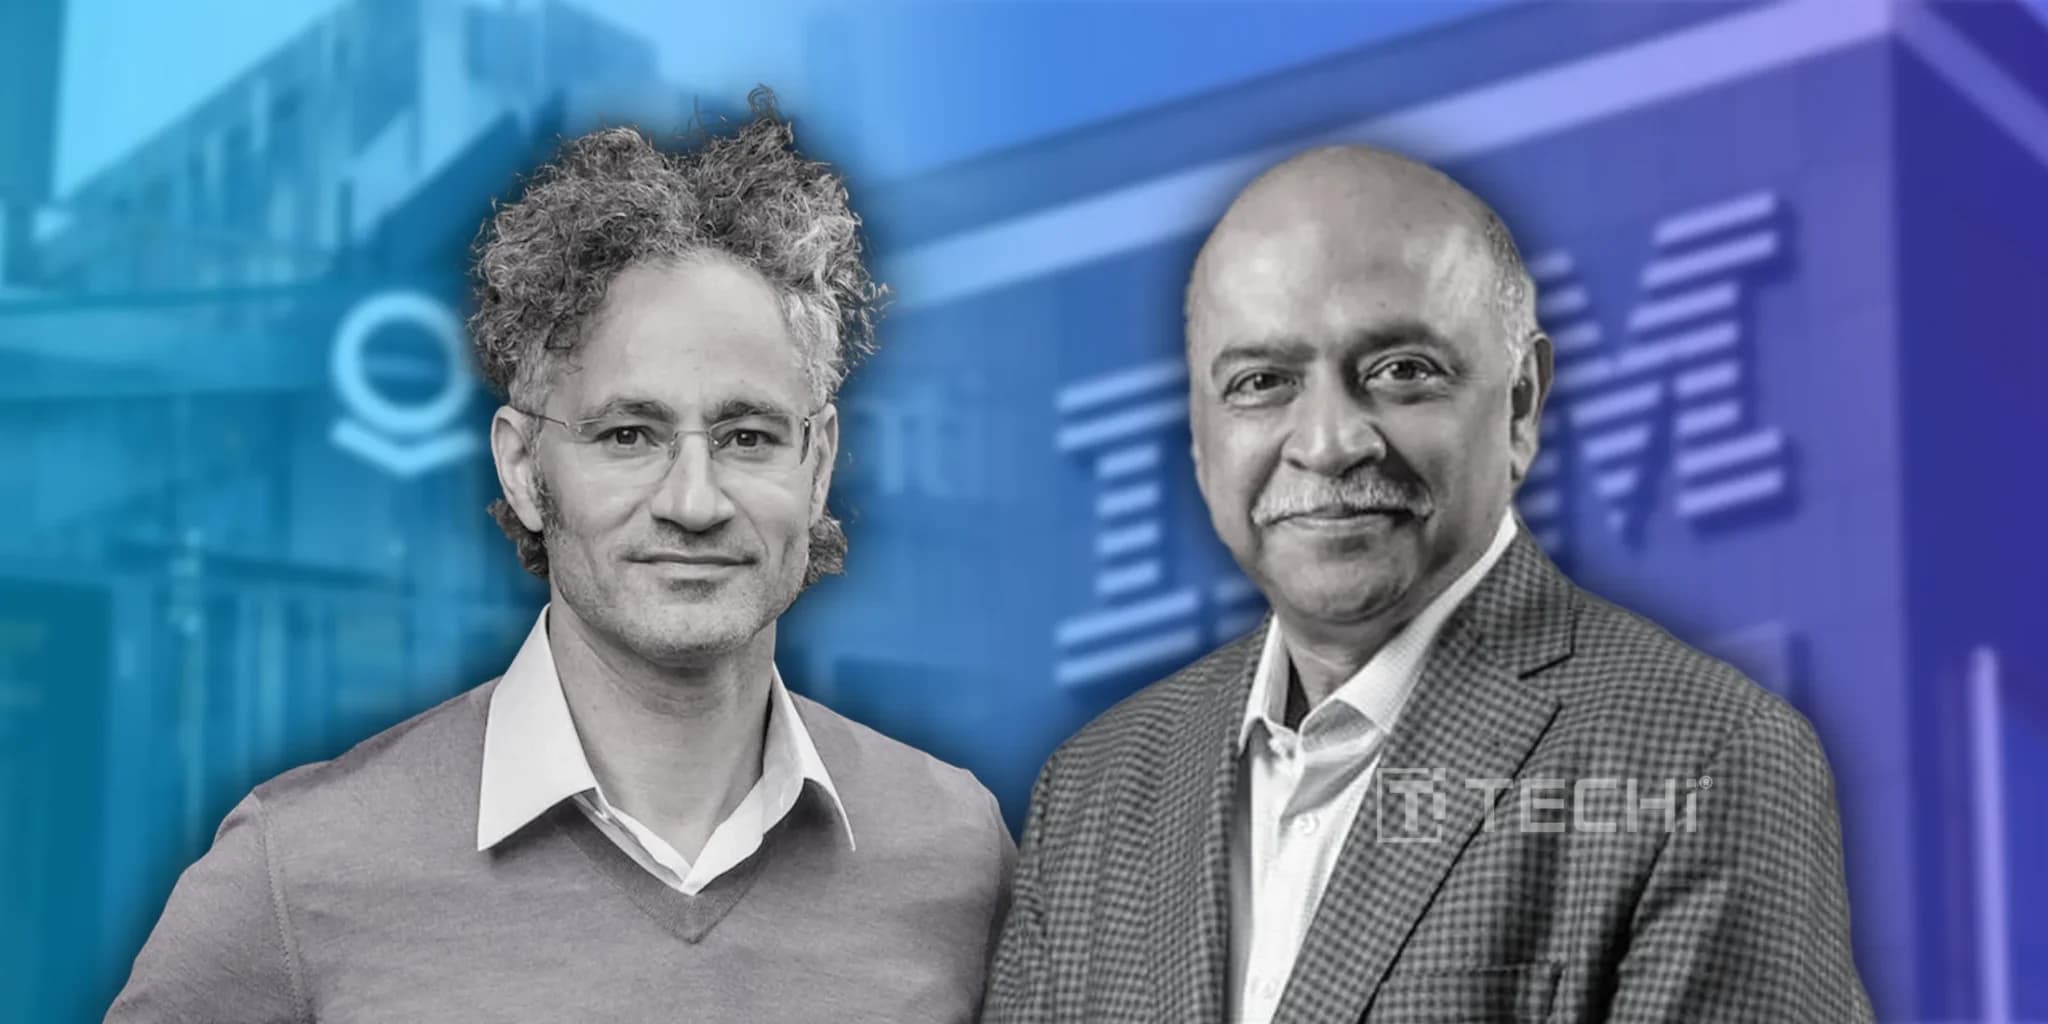
The world of defense technology has already started to speak of two enterprises: Palantir Technologies and IBM. With the growing government spending on AI-driven military-technological projects and militaristic innovation, more investor interest in long-term, sustainable growth is questioning such corporations.
The blistering rise of Palantir against the slow pace of change within IBM brings the central inquiry of who is best suited to provide sustainable value over the upcoming few years.
Palantir redefined Government analytics
For most of its history, the main output of Palantir was largely undisclosed information data-mining, mission-planning and its intrinsic use in serving both American commercial entities and national defense units across the globe.
Over the following years the company grew into a major contractor, winning high-profile contracts with the U.S. Army, the Ministry of Defence, and the Department of National Defence in Canada.
Governmental clients generate half of the revenues Palantir receives today, and the other half comes, historically, through commercial clients that use its Gotham and Foundry platforms to fulfill a variety of different business objectives: logistics and deep data analytics.
The thing is that Palantir has outstanding abilities in diversifying an ordinary picture of the world trends by considering the information of a great number of sources and consequently exceeding the resources of traditional analytics companies.
The application is used to plan missions, track each user separately, and even create custom AI resources that can be tailored to the exact needs of governments and companies. Palantir's revenue surged 47% in 2020 and 41% in 2021, but only rose 24% in 2022 and 17% in 2023 as it grappled with the uneven timing of its government contracts and fierce macro headwinds for its commercial business.
But in 2023, it turned firmly profitable as it streamlined its spending and reined in its stock-based compensation. In 2024, its revenue rose 29% as its net income more than doubled.
The Turnaround IBM: The Comeback of an Old Guard
As we can see, unlike in the meteoric rise of Palantir, the slow success of IBM is a more complex phenomenon. The company slump has been significant, as annual revenues declined for much of the decade after their 2011 peak.
Decades of legacy hardware, traditional programs, and outdated IT services put IBM at a disadvantage compared to other competitors, which have increasingly updated their approach toward more agile and cloud-based services.
This change has become a reality with a new CEO Arvind Krishna taking over in 2020. IBM recently refocused on shedding decelerating growth units, the biggest among them being the managed infrastructure services, currently known as Kyndryl, and redoubling its investment in hybrid cloud and AI software.
With the purchase of Red Hat, IBM provides open-source applications and deployable paradigms that help its clients to bridge internal servers and the public cloud applications.
The idea is that in this way, IBM will not have to compete with so-called hyperscalers (e.g. Amazon and Microsoft) but can instead securely carve its own niche in the hybrid-cloud market and develop its own portfolio of AI technologies.
Full-Year 2024 Revenue Growth
Indicator | Palantir (PLTR) | IBM |
2024 Revenue Growth | +29% | 1% reported (3% at constant currency) |
|---|
IBM’s full-year 2024 results report revenue growth of 1%, or 3% at constant currency. Palantir’s 2024 Form 10-K reports 29% revenue growth. These are annual actuals; revenue growth alone does not establish which stock will deliver better future returns.
What is the Actual Investment opportunity?
Palantir grew faster than IBM in 2024 on the reported revenue figures shown here. Its Form 10-K identifies competitors among enterprise software companies, government contractors and system integrators.
In case the forecasted growth indicators succeed, Palantir would see additional revenue and expanded market size, especially since the current external and internal conflicts promote the need of an AI serving military purposes.
Nevertheless, the risk associated with it is high. In the valuation multiples that it is currently experiencing and with meme-stock force, Palantir is vulnerable to engaging in severe corrections in case investor emotion swings or roll out opportunities in contracts. This makes time and entry price very sensitive factors that the potential investors give attention to.
IBM, on the other hand, offers an idea of changes and a capability to withstand. The company has realigned itself on a growth path through divestment of non-profitable units, increasing its focus on hybrid cloud efforts and Red Hat integration, address emerging productivity upgrades step-by-step, and create a comprehensive AI strategy.
IBM’s slower reported 2024 revenue growth gives it a different business profile. Its hybrid-cloud and AI strategy describes management priorities rather than a return investors can assume.
Looking into the Future
Surge in government AI spending and world security is also favorable to both Palantir and IBM. The innovative skill and quick implementation of Palantir has the potential to create further value-added particularly once the company ventures to new areas and signs more contracts.
The fact that the company has already re-branded itself, is keeping up to date as new markets emerge in terms of technology and is increasingly increasing its revenue and profits has already earned new respect.
The stronger historical growth rate does not establish which stock will outperform. A current comparison requires valuation, financial results and risks measured on clearly stated dates and consistent bases. Neither company can assure profits or protection from losses.

Disclaimer
This article is for informational purposes only and does not constitute financial, investment, tax, or legal advice. Market data, tax rules, and prices can change after the article date. TECHi and its authors may hold positions in securities or digital assets mentioned. Always conduct your own research and consult a licensed financial, tax, or legal professional before making decisions.
Comments