

Tokyo Electron’s fiscal 2027 forecast requires a stronger second half. TECHi editorial illustration using the Tokyo Electron logo from Wikimedia Commons (public-domain text logo; trademark retained).
Tokyo Electron shares rose 6.3% to ¥10,115 in Tokyo at 10:19 a.m. JST on Monday, November 2, according to a Yahoo Finance Japan exchange quote. Friday's close was ¥9,514. The move follows the chip-equipment maker's October 30 forecast for ¥1.169 trillion in operating profit in the fiscal year ending March 2027, up 87.1% from the preceding year. The forecast itself is three days old; Monday's share-price response is the new development.
The stock's more demanding test is in the second half of that fiscal year. Tokyo Electron's earnings release puts first-half operating profit at ¥506.8 billion and full-year profit at ¥1.169 trillion. Subtracting the first half leaves ¥662.2 billion for October through March, about 30.7% more than the first half. The company shows the same second-half estimate in its presentation, but the comparison is the point investors should carry into a forecast: the guidance needs another step up after an unusually strong first half.
There is a second, less obvious number in the October 30 documents. Tokyo Electron authorized a repurchase facility with separate limits of 25 million shares and ¥150 billion. At the observed ¥10,115 price, buying all 25 million shares would cost about ¥252.9 billion. The cash limit would instead cover about 14.8 million shares, or 0.65% of the 2.2698 billion shares outstanding excluding treasury stock cited in the notice. This is a price-based sensitivity, not a claim that the company bought any shares. The often quoted 1.1% share ceiling cannot be treated as an automatic reduction at Monday's price.
The ¥10,115 observation is a fixed publication snapshot, not a continuously updated price. Yahoo's underlying one-minute chart marked its last trade at 10:19:52 a.m. JST; it was about 15 minutes old when checked at 10:35 a.m. JST. The Tokyo Stock Exchange was in its morning session. At that quoted price, the stock was ¥601 above the October 30 close, or 6.32% using ¥9,514 as the denominator. A later trade can change the move without changing what this timestamped observation records.
Key Takeaways
- Tokyo moveTokyo Electron was up 6.32% at ¥10,115 at a 10:19 a.m. JST quote on November 2; the price may have moved since.
- H2 targetIts FY2027 guidance requires ¥662.2 billion of second-half operating profit, about 30.7% above the first half.
- Buyback mathAt the observed price, the ¥150 billion repurchase cash cap covers roughly 14.8 million shares, below the 25 million-share ceiling; no purchases are confirmed.
- Forecast testWatch recognized sales and operating margin against the company's October–March targets, not the one-day price move.
The profit hurdle behind the rally
Tokyo Electron's fiscal 2027 sales forecast is ¥3.7 trillion, 51.4% above the ¥2.4435 trillion reported for fiscal 2026. Operating profit is forecast at ¥1.169 trillion, compared with ¥624.9 billion last year. The resulting full-year operating margin is about 31.6%, up from roughly 25.6%. Those are company forecasts, not completed results. The demand explanation in the October 30 release is expanding investment in AI servers for data centers.
The first half is no longer a forecast. Tokyo Electron reported ¥1.6675 trillion in sales and ¥506.8 billion in operating profit for April through September. Sales beat its prior first-half estimate by ¥47.5 billion, or 2.9%; operating profit beat that estimate by ¥48.8 billion, or 10.6%. The difference between the two beat rates indicates stronger profit conversion than the earlier internal forecast assumed. It does not establish that the same conversion will continue through March.
To deliver the annual target, second-half sales must reach ¥2.0325 trillion, about 21.9% above the first half. Operating profit must reach ¥662.2 billion, about 30.7% above the first half. That means the implied second-half operating margin rises from the first half's 30.4% to about 32.6%, a gain of roughly 2.2 percentage points. The company provides those second-half figures and margins in its investor presentation. TECHi's forecast test is to place the needed sequential growth beside Monday's share-price rebound, rather than treat the full-year percentage increase as already earned.
The distinction matters because a stronger second half is doing two jobs at once: adding roughly ¥365 billion of sales over the first half and converting a larger share of that sales base into operating profit. If sales merely repeated the first-half ¥1.6675 trillion, the annual revenue target would miss by about ¥365 billion. If second-half sales reached ¥2.0325 trillion but its operating margin stayed at the first-half 30.4%, operating profit would be approximately ¥618 billion, about ¥44 billion below the ¥662.2 billion second-half target. These are arithmetic sensitivities using rounded company numbers, not alternative guidance from management.
What AI demand has to deliver
Tokyo Electron's management said in its earnings-call transcript that customers were requesting earlier deliveries and additional systems. It also said it had sufficient production capacity for second-half sales above ¥2 trillion. Those remarks support the feasibility of the company's plan, but orders, production capacity, shipped equipment and recognized revenue are different things. The forecast ultimately depends on customer spending converting into deliveries and sales during the six months ending March 2027.
The company estimates the global wafer-fabrication-equipment market at approximately $160 billion in calendar 2026 and more than $210 billion in calendar 2027, according to the October 30 investor presentation. The lower edge of the latter figure would be at least $50 billion, or 31.25%, above the former. That is a company market outlook, not a booked Tokyo Electron order total or an independent industry consensus. It would be a mistake to apply the market's estimated percentage directly to Tokyo Electron's shares, sales or earnings.
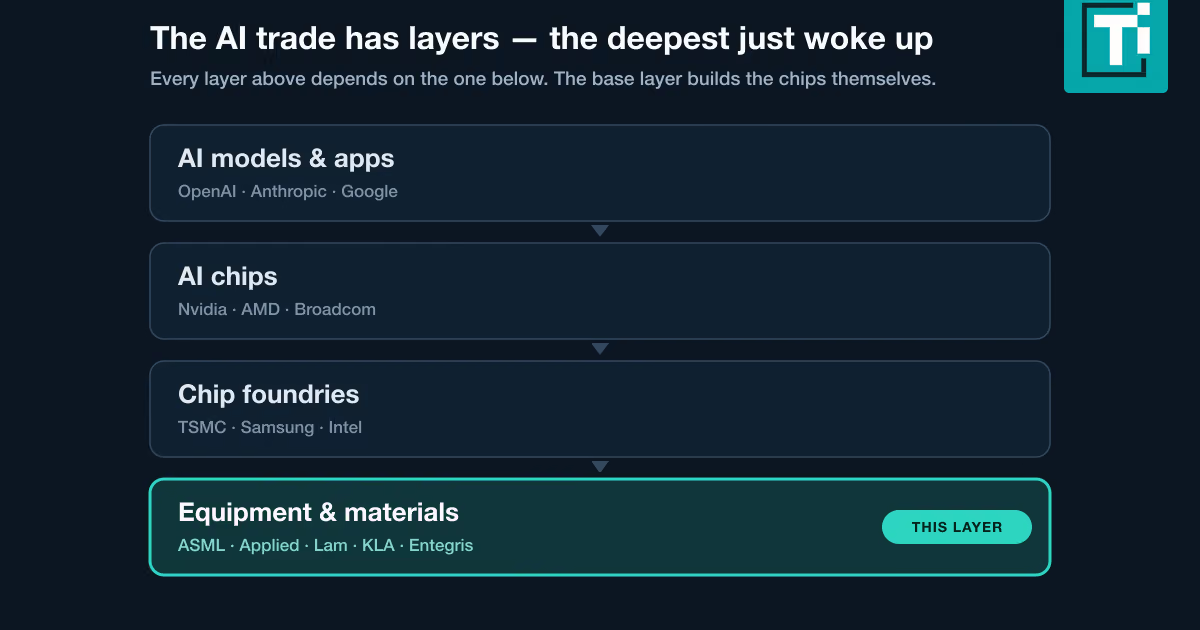
Management's AI argument also extends beyond the GPU. The transcript describes demand for high-bandwidth memory, DRAM, CPUs and NAND as AI applications use more compute and store more data. Tokyo Electron sells production equipment into multiple parts of that supply chain. That breadth is a potential advantage if customers keep investing across logic and memory, but it also means the stock's result depends on a collection of customer budgets and technology transitions rather than one AI product cycle.
That supply-chain breadth is a useful contrast with TECHi's Sandisk and Kioxia NAND analysis, which focuses on the storage side of AI demand. A NAND maker's selling price, a toolmaker's equipment order and a data-center operator's capital budget are connected, but they do not move in lockstep. A rebound in one stock is not evidence that every link in the chain has the same earnings exposure.
There is a geographic qualification. Management said China accounted for 36.4% of first-half sales, up six percentage points, and expected a low-30s percentage for the full fiscal year. That is a large exposure even if the second-half mix declines as forecast. Changes in Chinese customer spending, export controls, or delivery timing could therefore affect how cleanly the second-half target is achieved. The company has not published a scenario that isolates every one of those effects; investors should not pretend the ¥662.2 billion profit figure is immune to them.
A valuation check after the morning move
Tokyo Electron's earnings release forecasts ¥381.69 in net income per share for fiscal 2027. Its figures reflect the company's five-for-one stock split on October 1. Dividing the observed ¥10,115 share price by that forecast EPS produces a simple forward price-to-earnings ratio of about 26.5. The units and split basis match: post-split yen per share divided by post-split yen per share. This is a snapshot multiple based on the company's own forecast, not an analyst consensus valuation or a prediction of the closing price.
That ratio gives the market reaction a useful frame. A 26.5-times multiple can be defensible if a large equipment cycle and margin expansion persist; it becomes harder to sustain if the October–March profit step falls short. A lower share price alone would not make the company's ¥1.169 trillion target easier to achieve, while a higher share price would raise the multiple unless the earnings forecast also rose. The forecast needs evidence from customer investment, equipment shipments and reported margins, not a chart pattern by itself.
Tokyo Electron's repurchase notice says it may buy no shares at all, or only part of the authorization, between November 1 and March 31. A facility is authority to buy under stated conditions, not proof that shares were purchased Monday or that the company supported the morning price. The per-share forecast and forward multiple should be revisited if actual repurchases materially change the share count. For now, the clearer measurable driver is the operating-profit plan.
Three paths through March 2027
Base case: Tokyo Electron converts the already described customer demand into a strong second half, but the market waits for quarterly proof of the ¥2.0325 trillion sales and ¥662.2 billion operating-profit requirements. In this case, the current company forecast remains the working benchmark. The stock's 26.5-times simple forward multiple at the recorded price prices in substantial execution, so the next results matter more than a one-day rise.
Upside case: Orders and shipment timing stay firm enough for second-half sales and operating margin to exceed the company's stated estimates. That would strengthen the case that AI infrastructure spending is reaching equipment makers across memory and logic, and the full-year operating-profit target could prove conservative. An upside case requires verified new company results or guidance; Monday's share-price change alone cannot establish it.
Downside case: Customer spending slips or deliveries move beyond March, leaving second-half sales below ¥2.0325 trillion. If margins also fail to rise from the first half's 30.4%, the profit miss can exceed the sales miss. The ¥44 billion sensitivity above shows the cost of holding margin flat even when the sales target is met. Lower AI equipment demand, a weaker product mix, or regional constraints would have to be tested against later filings rather than assumed today.
The counterargument to caution is concrete. Tokyo Electron already beat its prior first-half operating-profit estimate by 10.6%, management describes requests to bring deliveries forward, and its published second-half forecast itself shows a record sales and profit plan. Those facts make the hurdle plausible. They do not turn it into a completed result. Investors following Tokyo Electron's TECHi quote page should distinguish the live or delayed market price from the dated company forecast and watch the next reported sales, operating margin and customer-spending commentary for evidence that the second-half bridge is holding.

Disclaimer
This article is for informational purposes only and does not constitute financial, investment, tax, or legal advice. Market data, tax rules, and prices can change after the article date. TECHi and its authors may hold positions in securities or digital assets mentioned. Always conduct your own research and consult a licensed financial, tax, or legal professional before making decisions.
Comments